


Economics Matters — Blog/Podcast/Financial Riddler/MaxiFi Puzzler
Sign up for a free subscription to all four products at larrykotlikoff.substack.com. I’ll immediately make it a lifetime subscription. But please support Economics Matters. Just unsubscribe and resubscribe here on a paid basis. Paid subscriptions come with a one-hour, free financial consultation. Email me to find a time at kotlikoff@gmail.com. You can unsubscribe and resubscribe for free. Also, please sign up kids, friends, colleagues, students, … !
Is Your Annual Budget Remotely Correct?
It’s the new year — time for all of us to figure out how much to spend each month, each week, and even each day to stay within our annual budget. Whether we’re scrutinizing our credit card bills, using Excel, or mastering the latest slick online budgeting tool, the goal is the same — deciding how to spend within our means on everything from rent to groceries, to clothes, to vacations, to home repairs, to Milk Duds.
Figuring out how to allocate our annual budget is vital. How else can we get the most pleasure — what economists call utility — from what we spend? Yes, we can pig out on three Starbucks grande caramel nonfat, iced latte, with extra caramel drizzle a day. And, yes, it’s Taylor Swift’s favorite. But she can afford the $7,115 annual cost. We can’t —at least not in terms of the sacrifice needed to feed that habit.
Recall what you learned in EC101 (and don’t start perspiring). In deciding how much to spend on X versus Y, we try to equalize marginal (extra) utilities. At the optimum, if I spend a dollar more X and a dollar less on Y, the loss in happiness from foregoing a dollar’s spending on Y has to equal the gain in happiness from spending that dollar on X. If that weren’t the case, if an extra dollar spent on X produced, say, 10 times more happiness than an extra dollar spent on Y, than, my original allocation could not possibly have been best (optimal).
Getting the Budget Shares Perfectly Right, But the Total Budget Completely Wrong
But how do you know if your monthly and, thus, annual spending target is, in fact, on target? Clearly, the more you spend on ice cream, the less you’ll have to spend on steak, let alone that vacation to Atlantic City. But the more you spend in total this year, the less you’ll save and, therefore, the less you’ll have to spend in future years.
The rule of equalizing marginal utility across different purchases in the current year also applies to allocating your lifetime resources across different years. You seek an annual spending path that equalizes the marginal utility of spending across different years. In plain English, you don’t want to spend an extra dollar this year if that dollar could be saved and spent (including accumulated interest) later generating more lifetime utility.
Allocating your lifetime spending power optimally, across current and future years, is what economists called consumption smoothing. It’s also called lifetime budgeting — because you’re deciding how to allocate your lifetime budget — your current assets plus current and future labor earnings — between this year and future years.
DIY Lifetime Budgeting without the Bespoke, Precision Software Is Just Hopeless
Lifetime budgeting may sound easy. It’s not. In fact, it’s impossibly difficult without the right technology. And AI, unless it’s been trained on the right answers using that technology, is and will remain entirely hopeless. Let me illustrate for the case of Sarah and John. They are one of our country’s 134 million different households. Some are single. Some married. Some bearing crushing debt. Some expect fabulous inheritances. Some live in high-tax states. Some are terribly house poor. Some take financial care of older parents. Some have disabled children. Some are widowed. Some are as young as springtime. Others are close to death’s door.
You get the point. Each household is unique. But even seemingly small differences, like whether a household’s retirement assets are taxable upon withdrawal (e.g., in a traditional IRA) or not (held in a Roth IRA) can materially alter their discretionary annual spending budget. I say “discretionary,” because that’s the only thing households can control. Their housing, alimony, college tuition, care for their infirmed parent, current or prospective—all our out of their control. Federal and state taxes, including taxes on Social Security benefits, the Additional and High-Income Medicare taxes, and the Medicare Part B IRMAA tax are also forms of fixed/non-discretionary spending.
But they do depend on your discretionary spending for a simple reason. The more you spend, the less you save, and the less you save, the less asset income you’ll have down the road. But the less asset income you’ll have, the lower will be your income and other taxes. So, discretionary spending impacts taxes. But taxes also impact affordable annual discretionary spending. In short, there is a massive chicken and egg problem in the middle of lifetime and, thus, annual, monthly, weekly, and daily budgeting.
Thus, this familiar warning applies to proper budget over any period:
Don’t try this at home.
Could Deep Blue figure this out? Not in a million years, without the right code. Could the most powerful LLMs? No. They are spitback machines, trained on wrong answers to provide wrong answers. Let me illustrate with a quick
Guess the Right Discretionary Budget Game.
Meet Sarah and John
Pretend you are Sarah and John and tell me their annual discretionary spending budget for this year assuming they want to maintain their living standard through time, can’t borrow against future income, like Social Security benefits, to finance current discretionary spending. In econ jargon, they are potentially cash-flow constrained.
Sarah, age 41, and John, age 46, live in Iowa. Sarah earns $100K annually1, John earns $60K. Sarah projects her earnings to grow 1 percent faster than their assumed 3 percent inflation rate and John projects his to grow 1 percent slower. Both Sarah and John expect to retire together and take Social Security in 2047, when Sarah is 62 and John 67. Sarah started working at 22, earning $35K, experiencing 3 percent nominal wage growth each year.
Why do you need this earnings history? Sarah’s past as well as future covered earnings will determine her future Social Security benefits, which play a critical role in the couple’s lifetime budgeting. Sarah will also receive a $25K nominal pension from a private job starting at 66.
Sarah’s $350K 401(k) is being fattened annually thanks to equal $1,500 employee and employer contributions, which will keep even with the real growth in her salary. She’ll start withdrawing from this account smoothly in real terms when she retires.
How about John’s earnings record? Well, John immigrated at 40 to the US from Australia, earning $52,117 that year with 2 percent nominal wage growth through the present. John will receive a $35K inflation-indexed pension starting at 63. John has a Roth IRA with just $25K in assets to which he’ll contribute $7K through retirement. He’ll also start smooth, real withdrawals when he retires.
What else about the couple? They have $750k in regular assets, live in Iowa, own a $500K house, free and clear, with $20K housing expenses that keep up with inflation. They intend to die in situ, i.e., in their home. Their main obligation is supporting Sarah’s mom to the tune of $40,000. She’s 65, and they’re giving her 30 years to meet her maker.
Last thing. The couple plans on earning a 5 percent annual nominal return on their savings, meaning their annual real return is 1.94 percent.
Guess Sarah and John’s 2026 Discretionary Spending Budget
How much can Sarah and John spend this year, on a discretionary basis, such that they can have the same living standard each year in the future if they both live to 100 — with the caveat that their future living standard will be higher if they run into cash-flow constraints?
Clearly, this is a brutally complex problem. You need to jointly consider all the federal and Iowa tax considerations, properly incorporate inflation, understand the determination of Social Security benefits, not to mention handle the chicken and egg problem. Oh, and there’s also life insurance that both spouses may need to purchase to ensure their partners can maintain the same living standard if they die before 100 — their maximum ages of life. Those life insurance calcs need to account for the taxes survivors will pay in each future year depending on when they become widow(er)s. Incorporating life insurance purchases is important because the premiums on those policies are, yet, another component of off-the-top/non-discretionary/fixed spending. And the more such spending, the less left over to cover discretionary spending.
And the answer IS?
$171,943
$143,308
$122,073
$98,476
$59,119
If your answer is “No clue,” you’re with me. Before I ran my company’s, MaxiFi Planner software — in the half second it took just now, I also hadn’t the slightest clue. And I developed the tool’s code, including its patent-winning iterative dynamic programming. By analogy, consider Deep Blue, the 1997 computer chess program that beat Gary Kasparov, then the world’s chess champion. Its programmers can’t beat it, let alone far more advanced computer programs.
A Little Digression While You Consider Your Answer
I started MaxiFi (Economic Security Planning is the company’s formal name.) with the goal of providing economics-based financial planning to the public. Economics is an almost entirely descriptive science. I thought and think it needs to be a prescriptive science, providing the public correct answers, not endless analysis of their mistakes — the (to me) badly misguided goal of behavioral finance.
MaxiFi handles all aspects of financial planning — lifetime budgeting/consumption smoothing, estate planning, Social Security benefit maximization, Roth conversion optimization, taxable retirement withdraw optimization, life insurance needs, the value of annuitizing, children, housing decisions, real estate, investing for the upside with a living standard, choosing your optimal time-varying portfolio, … — you name it.
“Economics” is scary to most people. But MaxiFi is not. Check out these testimonials, Bankrate’s naming MaxiFi “The Best Financial Planning Software of 2025," or financial influencer, Rob Berger’s naming MaxiFi, among the “5 Best Retirement Calculators.” (Note, MaxiFi can be used by anyone at any age for any decision. So, it’s not just about retirement.) Or peruse these 100 top media stories about MaxiFi.
And Your Answer Is ?
Let me give you a “clue.” I copied all of the above verbatim into Perplexity AI and ask it for the answer. Here’s that it said, “Sarah and John, your 2026 annual discretionary spending budget is $83,000. This maintains $83k real constant standard (post-inflation), adjusting up later if surpluses (e.g., post-mom).” Next I asked it for their discretionary spending when John is age 65, 75, and 85. In each case it responded with $83k in real discretionary spending.
The Right Answer
The right answer is $122,073. It’s also $127,613 when John’s age 65. But when John’s 75 and 85, it’s $159,136. Hence, what some claim is the top AI tool told the couple to spend 35 percent too little for the next 25 years, year in and year out and then 48 percent thereafter. Mind you, this is a deterministic problem. There is only one correct consumption smoothing answer subject to cash-flow constraints.
If supposedly genius LLMs can’t get within a mile of the right answer and the developer of the tool that does get the right answer can’t get within a mile of the right answer without using the tool, maybe it’s time to use MaxiFi to figure out your proper annual budget because you are surely budgeting, again, maybe to within pennies, to precisely the wrong annual total.
Trust, But Verify
How can one check that MaxiFi’s Lifetime Budgeting is correct?
Just look at its first report. It shows that the Sarah and John’s lifetime budget balances. The present value of their fixed spending, including taxes, shown in gray plus the present value of their discretionary spending, shown in green, equal, to the dollar, the present value of their resources.
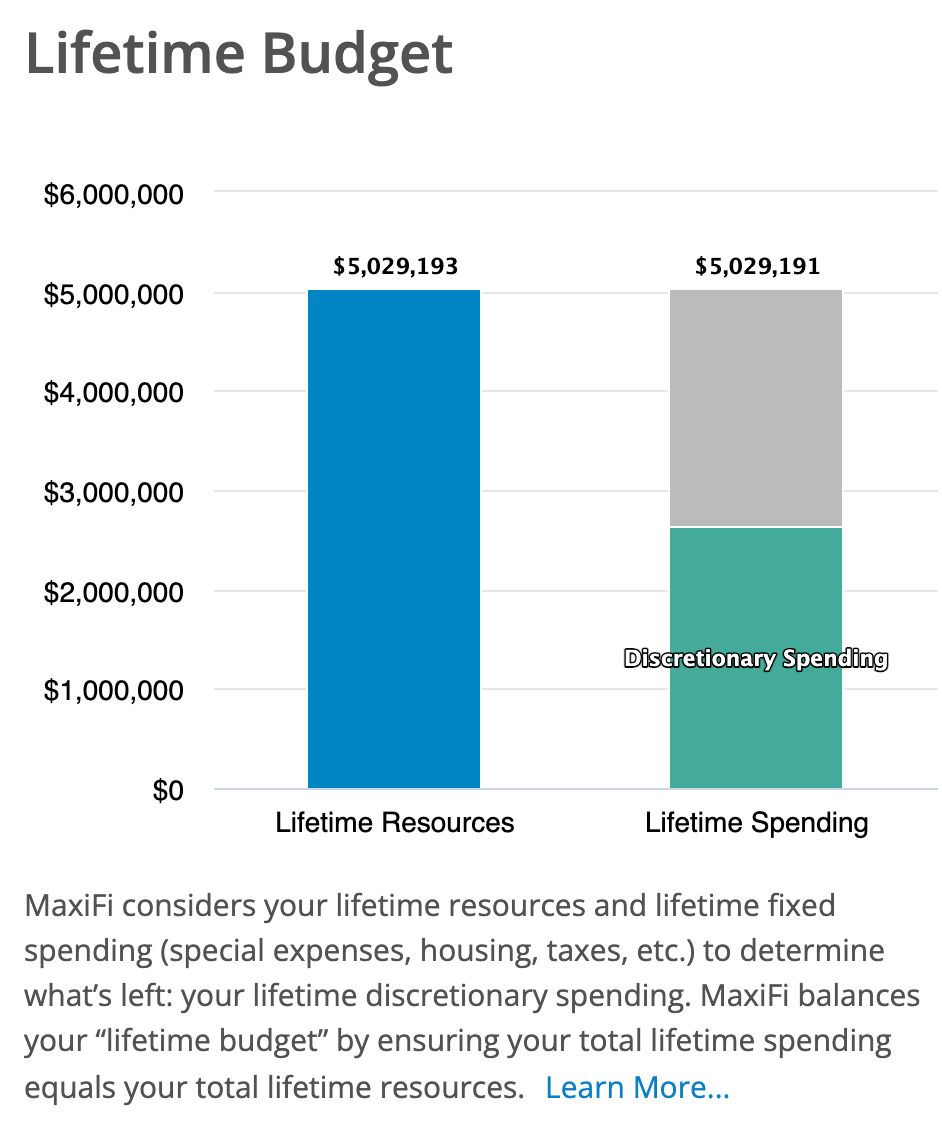
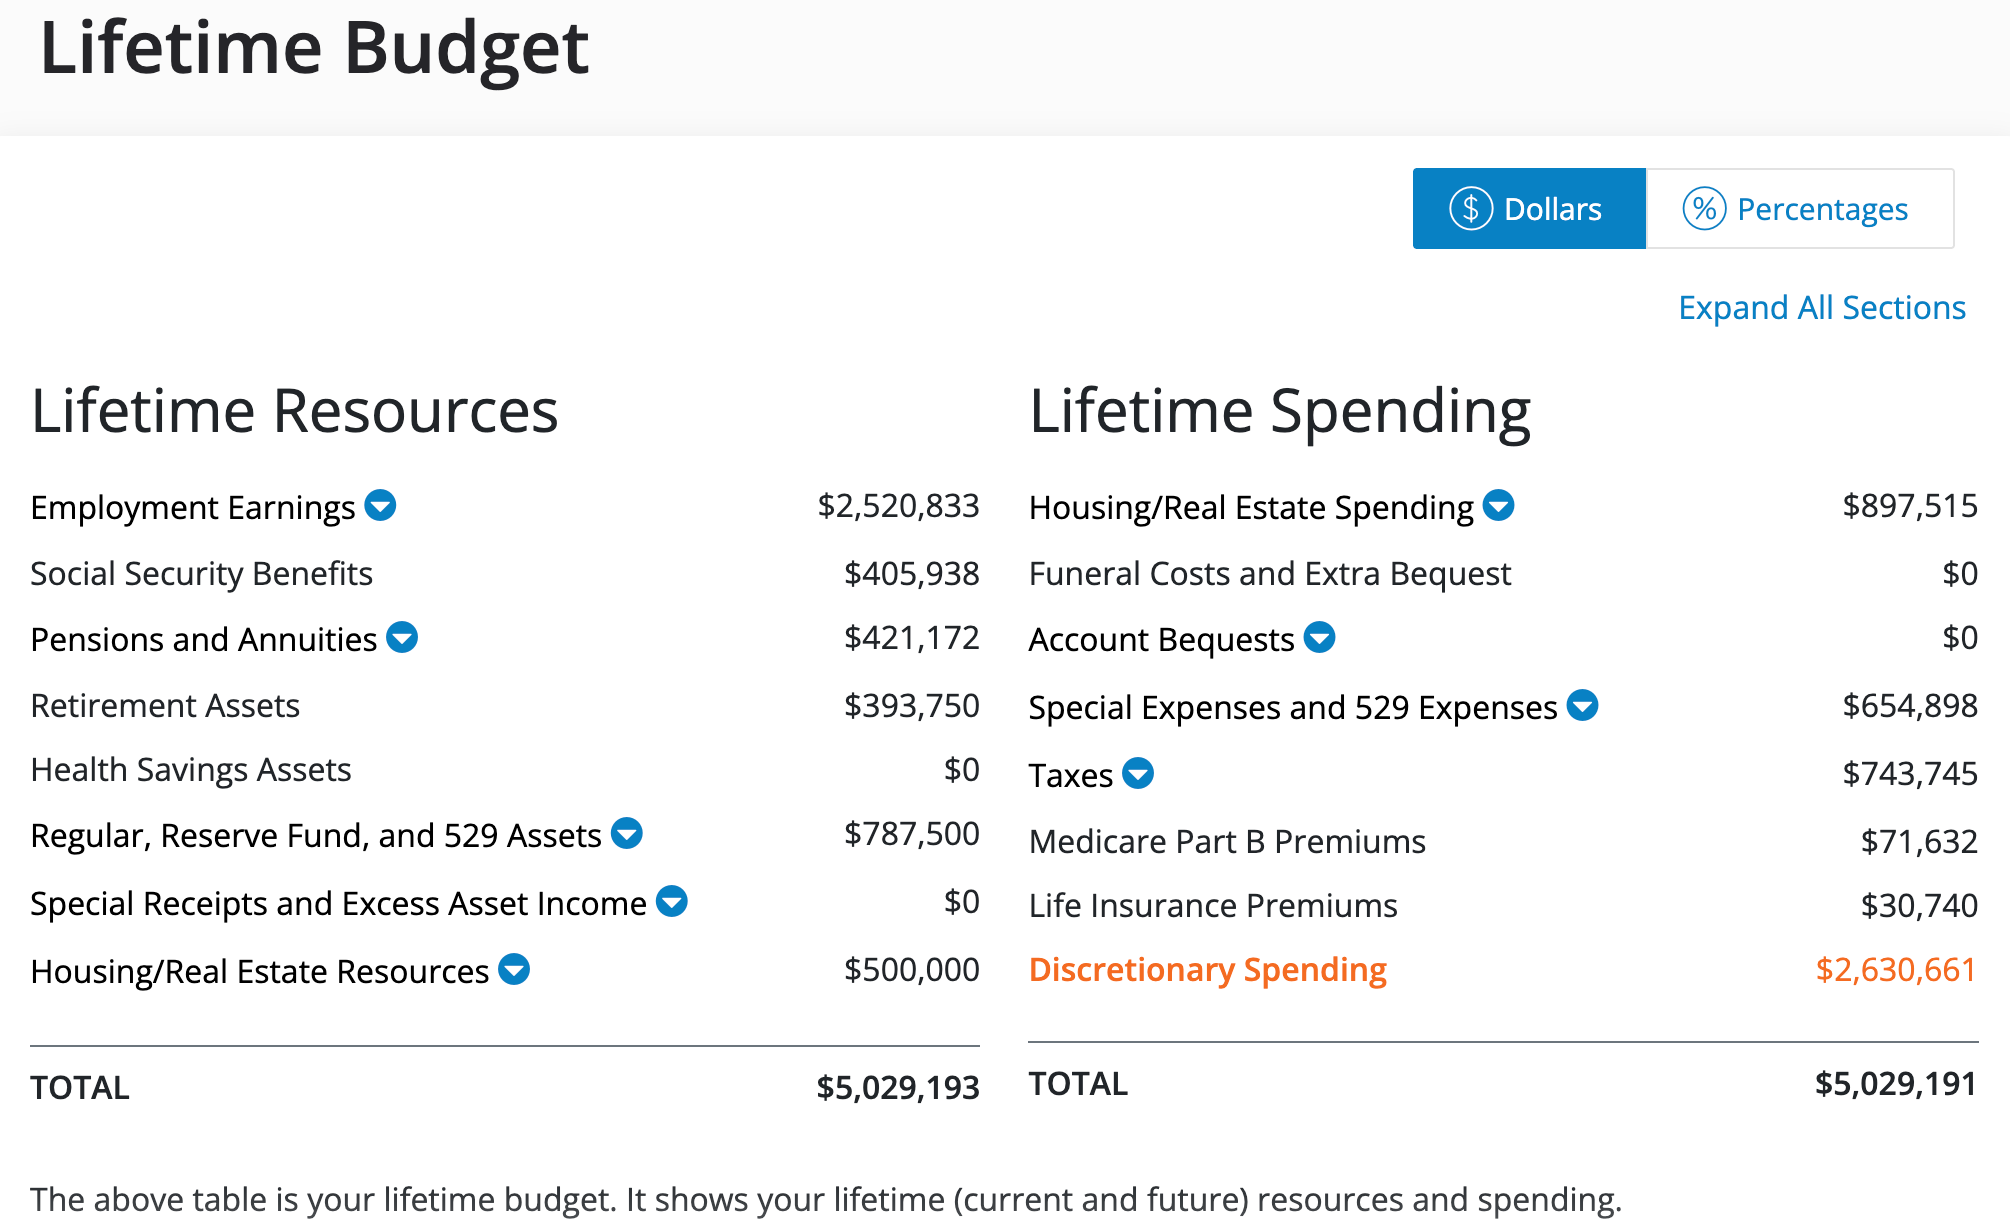
The next chart shows the lifetime budget in detail.
And this chart show annual discretionary spending in today’s (real) dollars.
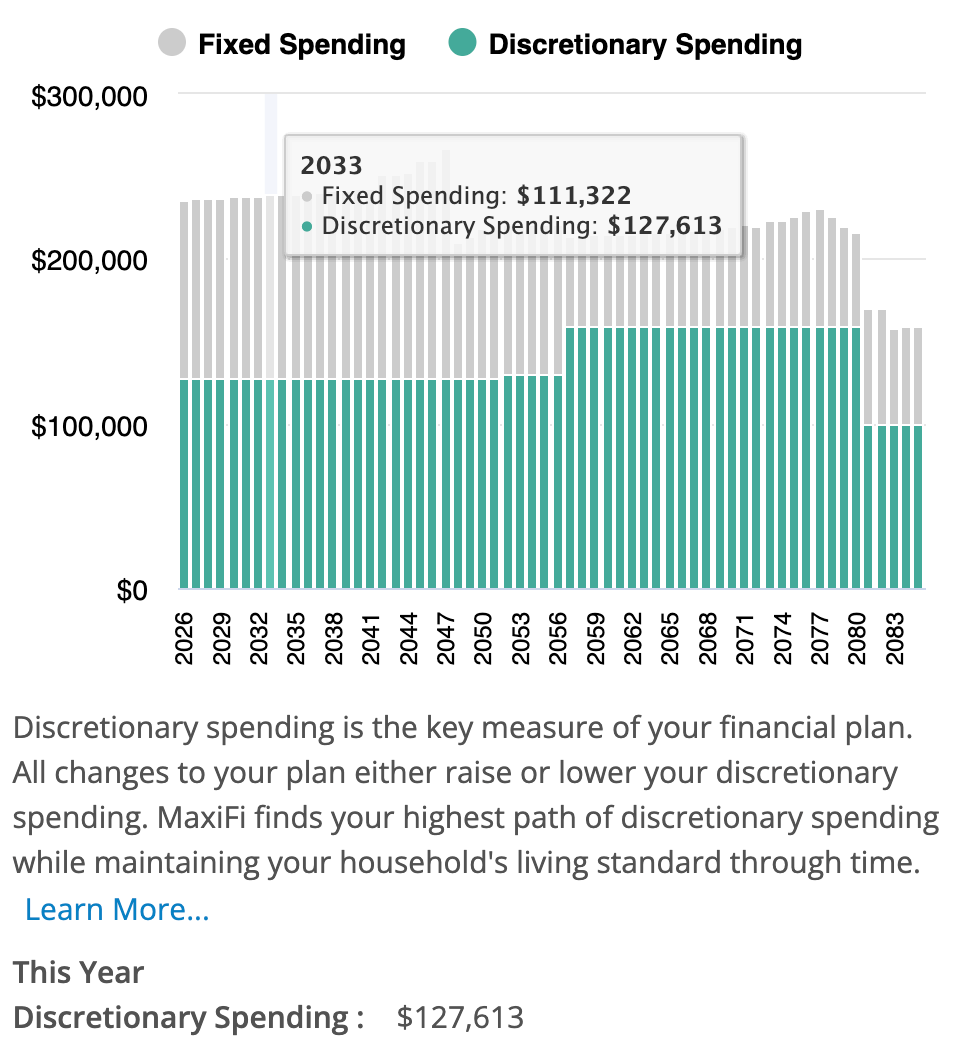
If the annual discretionary spending were off, even $5 each year, Sarah and John’s lifetime budget wouldn’t balance. Hence, the only way things could be wrong is if taxes or Social Security were miscalculated. But MaxiFi follows federal and state current and projected annual tax returns and has a ream worth of computer code to precisely capture all 22,000 pages of Social Security rules governing its 12 benefits. (Why 22,000 pages of rules for so few benefits? The system is the most complex bureaucratic nightmare yet devised by man. It has, for example, not one, but six different widow(er)s benefit formulas.
Bottom Line
Budgeting is important, but it’s pure folly if you don’t have the right budget with which to start. Sarah and John spent $109, purchased MaxiFi, and a half hour later discovered that they could spend $127,613 this year or $10,634 a month or $2,659 a week, or $87 a day.
And now ads from your sponsor — ME!
Larry, I'm confused by the numbers. With total employment earnings of $160k/yr this year, total fixed + discretionary spending of about $239k/yr (in 2033, so slightly less this year) seems imprudent. The bottom graph shows total spending > $200k/yr most of the 59 years in their planning horizon. Call it $200k and 60 years, that's $12M lifetime real spending - which doesn't match the table showing $5M total real spending. What am I doing wrong?
This is a strong argument for why annual budgeting misses the point and why lifetime resource planning is the right frame. One dimension that remains largely implicit, however, is healthcare — not merely as a retirement expense, but as a variable liability that reshapes the feasible lifetime budget itself. Medical bills remain the leading cause of family bankruptcy in the U.S., and roughly 44% of households are uninsured or underinsured. Health risk affects timing, volatility, and drawdown in ways that standard consumption-smoothing models don’t fully capture. Two households with identical lifestyles, assets, and consumption patterns can follow very different sustainable paths once health trajectories diverge. This raises an important question: how should lifetime budgeting frameworks evolve when health is treated as a dynamic financial variable rather than a static line item?