


Economics Matters — Blog/Podcast/Financial Riddler/MaxiFi Puzzler
Sign up for a free subscription to all four products at larrykotlikoff.substack.com. I’ll immediately make it a lifetime subscription. But please support Economics Matters. Just unsubscribe and resubscribe here on a paid basis. Paid subscriptions come with a one-hour, free financial consultation. Email me to find a time at kotlikoff@gmail.com. You can unsubscribe and resubscribe for free. Also, please sign up kids, friends, colleagues, students, … !
Financial Therapy
I wear lots of hats. One is a self-styled financial “therapist.” No, I’m not a licensed mental health professional. But I do talk with many people about their finances in providing MaxiFi Planner’s Concierge Planning Service.
In the process, I’ve encountered a goodly number of households, rich and poor alike, unwittingly engaged in what I call downside investing — investing with the sole, if unintended purpose of potentially making themselves worse off. The good news is that this financial masochism is not entrenched. Once people realize it, they switch their holdings.
Let me describe the financial pathology. But first, some background on MaxiFi - my company’s financial planning software, which I use to diagnose the disease. The software is 33 years in the making. Its patent-winning technology solves the fundamental equations of finance, delivering economics-based financial planning. These equations were developed over the past century by a Who’s Who of personal finance wizards, including Irving Fisher, John von Neumann, Oskar Morgenstern, Milton Friedman, Kenneth Arrow, Harry Markowitz, James Tobin, William Sharpe, Franco Modigliani, Menachem Yaari, Paul Samuelson, and Robert Merton.
Their work comprises the core of personal financial science and is taught in every top finance and economics department across the globe. MaxiFi is also becoming part of this curriculum. To quote Nobel Laureate, Robert Merton,
“I assign MaxiFi Planner in my asset management course at MIT’s Sloan School of Management as an outstanding science-based lifecycle and retirement management platform.”
Don’t Sweat the Equations
If reading the word “equation” makes you sweat, grab a towel. MaxiFi does its math under the hood. Above the hood, it’s easy as pie. Indeed, the program can be used by 12th graders. In fact, here’s my offer to high school teachers.
If you teach high school seniors and want free licenses to MaxiFi for yourself and your students, email me at kotlikoff@gmail.com. Have your kids plan for their parents as their homework assignment! Financial literacy courses teach financial lingo, explaining terms like discounting, equities, and budgeting. But knowing what the words mean doesn’t tell you what the moves mean — for a good reason. Using just your noggin to making correct financial moves, like beating a master computer chess program, is beyond human capacity. Using MaxiFi will teach your students the moves as well as the words, delivering effective rather than surface financial literacy.
My claiming the tool is extremely user friendly as well as incredibly powerful is one thing. Bankrate’s naming it “Best financial planning software of 2025” is another. Kiplinger, Well Kept Wallet, and major financial planning influencer Rob Berger, also just ranked MaxiFi best of class. And, as these 100 plus testimonials testify, MaxiFi can be used by all ages at all phases.
Downside Investing — Investing at Risk while Spending Below your Safe Level
Hypothetical Sandy Black illustrates downside investing. Sandy is a born and bred Upper East Side New Yorker. She’s 65, retired, and lives in a tony co-op on 85th and Madison worth $3 mil. Her pad costs $95K a year in insurance, property taxes, and coop fees. Sandy intends to die in situ. If she needs a nursing home, she’ll sell. But they’ll need to drag her out kicking and screaming. To cover home healthcare, she’s specified $100K, in today’s dollars, as an annual special expense starting at age 85 and continuing through age 100, her maximum age of life. Sandy is an only child. Her husband died during COVID. They never had children.
Sandy is both frugal and thin. Apart from her off-the-top expenses, she spends $83,523 annually, on food, opera tickets, theatre tickets, the NY Times (daily print delivery), a monthly trip to Katz’s Deli, groceries, home supplies, cleaning, and other discretionary spending. Sandy would love to take a cruise, but she’s worried about her finances, particularly her stock investments. Sandy has 80 percent of her assets in an S&P index fund with the rest in a diversified bond fund.
What assets?
Sandy has $5 million in regular assets and $5 million in an IRA. Yes, she knows the market’s risky, but she thinks she needs its high average return to survive for what could be another 35 years. Her recurring, 5 AM nightmare, is that the market crashes and doesn’t recover. Michelle, her new neighbor down the hall, is a stock broker and tells her, “Don’t worry. The market always recovers. And if you invest with me I’ll beat the market, which I’ve done 20 years running. The fee is only 1 percent — just $100K a year.”
Sandy’s Safety-First Spending Plan
Hypothetical Sandy hypothetically signed me up to run her through MaxiFi. MaxiFi’s first task is to do fiduciarily responsible, safety-first, lifetime planning. This entails determining how much Sandy can sustainably spend on a discretionary basis if she invests in the safest asset around, namely TIPS — Treasury Inflation Protected Securities.
TIPS are Treasury bonds that adjust coupon and principal payments every six months for the ensuing inflation. When I ran Sandy’s plan, the real return on 10-year TIPS was 1.76 percent based on a 4.04 yield on nominal 10-year Treasuries. This implied a 2.27 percent inflation rate. I entered these rates into the program.
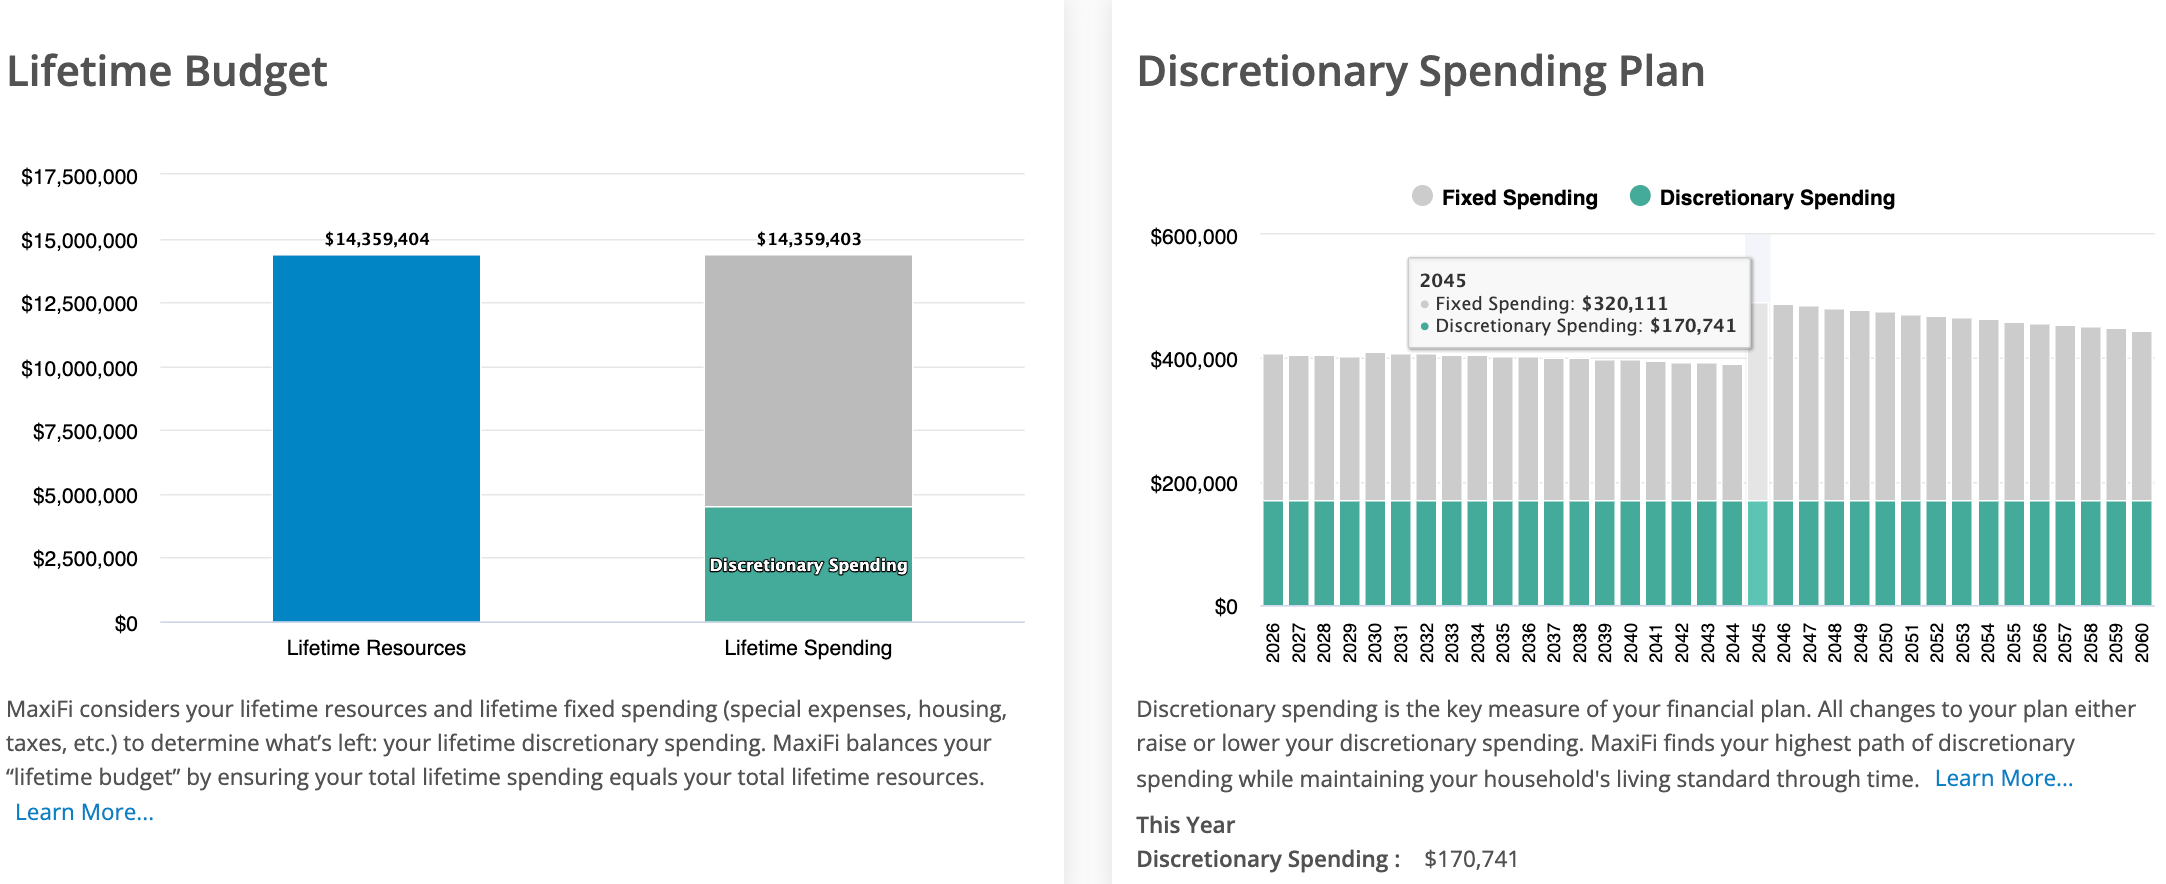
As Sandy sat across from me in the Zoom, I told her, “I have very good news. If you invest safely — in a ladder of TIPS that yields, on average, 1.76 percent after inflation — you can afford to spend $170,741 in today’s dollars straight through age 100. And this is your discretionary spending budget! It’s after you cover all your fixed expenses on housing, taxes, and 15 years of home health care. $170,741 is more than twice your actual annual discretionary spending!
To be clear, I’m NOT advising you invest in TIPS. I’m NOT a certified investment advisor. I’m just here to explain MaxiFi’s results. Everything has risks. Who knows? Uncle Sam could decide to default on federal debt. But that seems extremely unlikely. The point is that if you can earn 1.76 percent real, on average, on your investments, you can afford to take seven luxury cruises every year for the next 35 years!”
Sandy was incredulous. “I’m not worried about default. That would destroy our entire financial system. Even Trump wouldn’t and couldn’t get away with debt default. But how do you know your program is correct? To me, it’s a black box.”
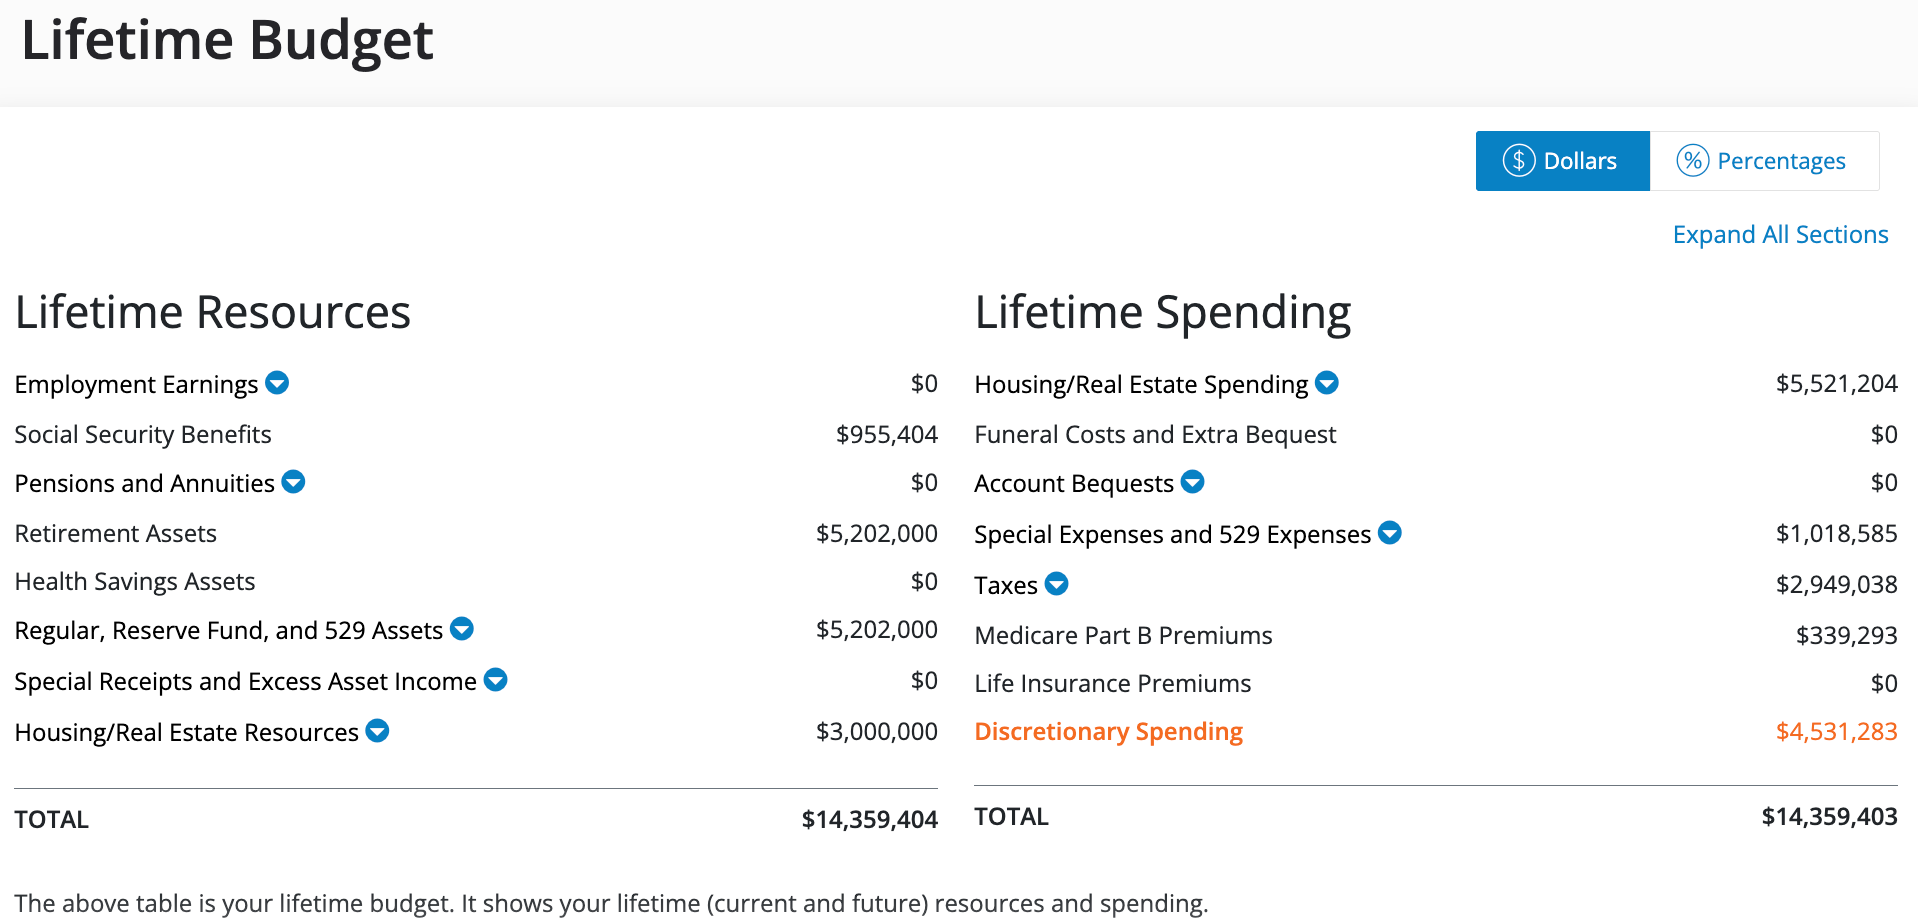
“Take a look at your lifetime budget constraint, Sandy. It balances to the dollar. It shows all your resources and all your outlays — in present value. If the program wasn’t working, your discretionary spending wouldn’t be smooth (unless you were cash-flow constrained, which you aren’t) and your lifetime budget wouldn’t balance.”
Sandy Only Has Downside Risk
“Sandy, can you see your way to spending more — to having more fun with your money?”
“I can take one cruise a year, but not seven. Yes, I’m excited by that prospect. But I don’t see spending more than another $10K at most. I’m just not a spender. And what about my stocks? You’re talking about a 1.76 percent maturity-weighted real return on a TIPS ladder. I can earn over 7 percent real on the market?”
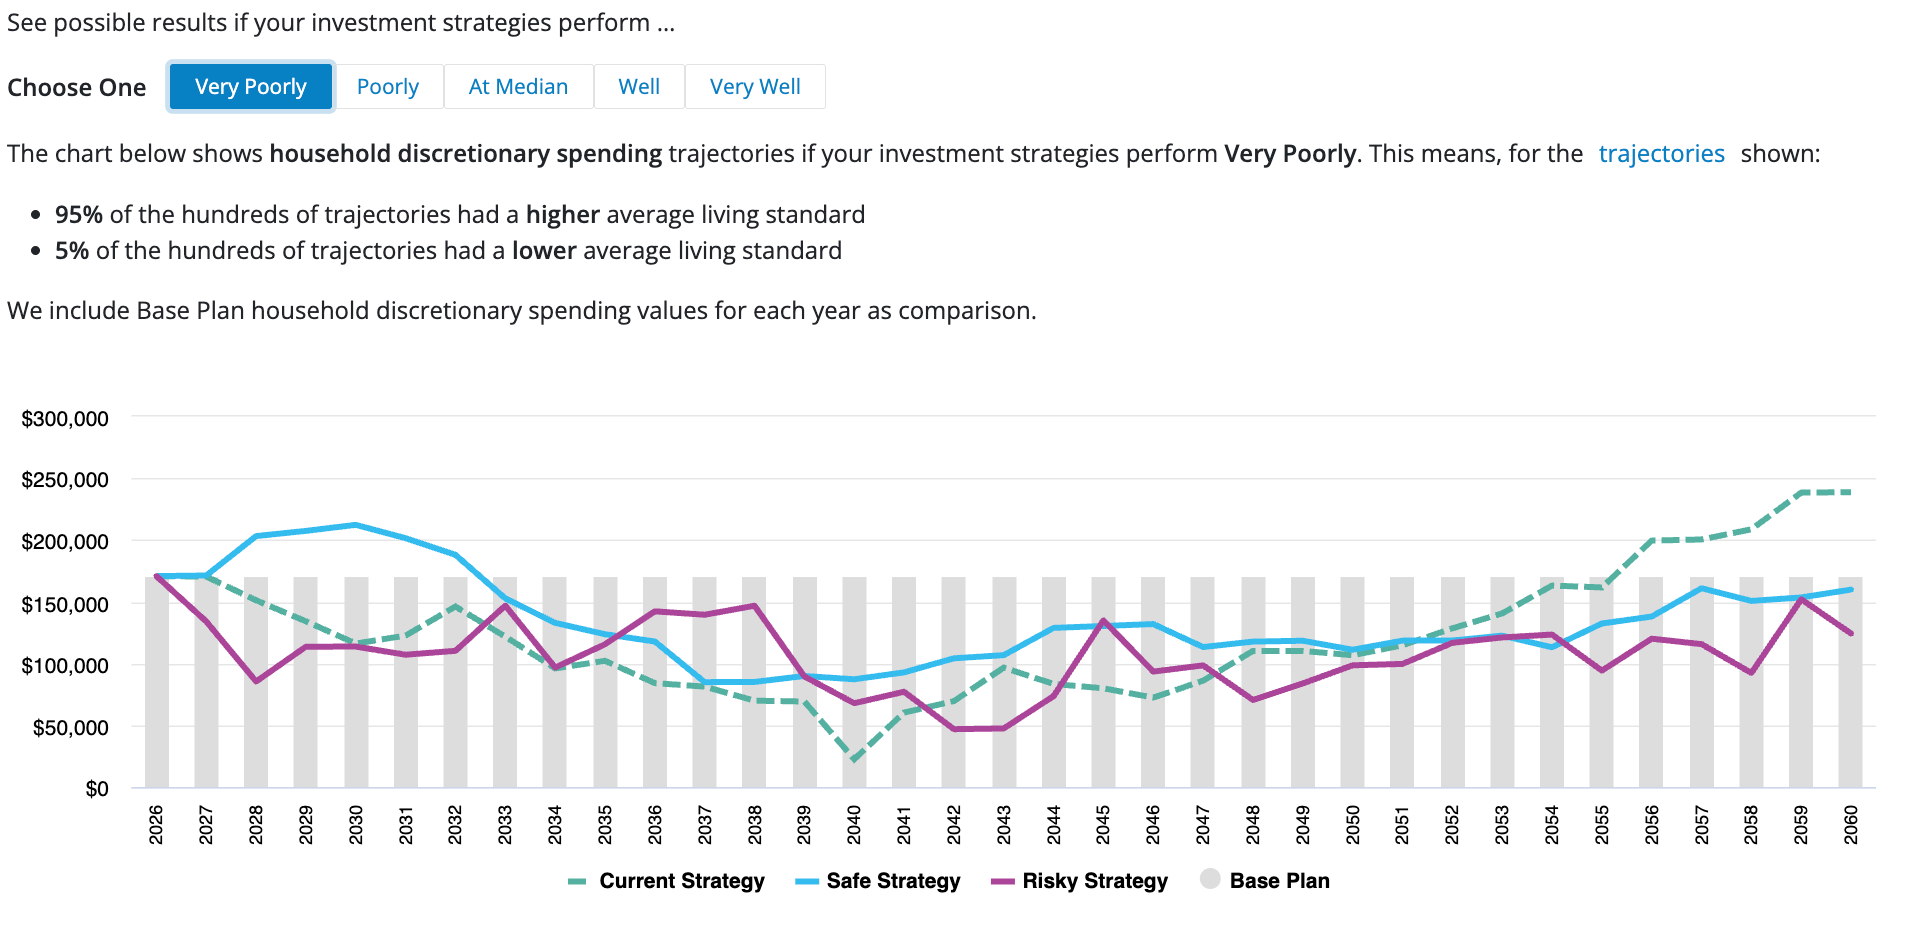
“Yes, on average, Sandy. But the return on the market is highly risky. I just ran your 80-20 stocks-bonds portfolio through MaxiFi. Take a look at the chart below. The red curve entails investing 80-20. The green curve is 50-50. And the blue curve is 20-80.
The chart shows the 5th worst discretionary spending trajectories you could experience under each investment strategy. That’s what we mean by doing “Very Poorly.”
MaxiFi produces 500 trajectories for each of strategy. The trajectories rise and fall depending on how well you do on the market each year. I.e., MaxiFi adjusts annual spending in light of annual investment returns. The 500 trajectories for a given investment strategy are ranked from highest to lowest based on the average living standard across all of your 35 possible future years.
Note that investing 80-20, as you are now doing, runs the risk of having less discretionary spending every year in the future than the $170,741 per year — what you could afford to spend annually if you invest safely at 1.76 percent real. Yes, because you are spending a lot less than you could, you’re creating a cushion against losing money on the market. But when I ran MaxiFi setting a ceiling of $93,523 on your annual spending — what you’re now spending on a discretionary basis plus $10K for a once-a-year cruise — the program shows 7 out of 500 trajectories in which you completely run out of money and need to sell your co-op!
So, Sandy, assuming TIPS are safe, you are investing just for the downside. If the market does well, you aren’t going to spend more. If it does poorly, indeed poorly enough, you’ll be moving to Tennessee. Yes, the market has been your friend in the past. But it may kill you in the future. And to what end? Again, if it does well, you gain no benefit. If it does poorly, indeed, poorly enough, you end up getting hurt — potentially very badly hurt.
Sandy, investing just to lose money, which is the only thing the market will do to your living standard, makes no sense. It’s financial masochism. Do you get my point?”
“Yes, hypothetical Larry, I get your point. Given I’m spending as much as I want and given I can more than, indeed far more than maintain my living standard if I invest safely, there is NO reason to invest at risk. Absolutely none. If my stocks do well, I’ll just have more money that I can’t spend. If they do terribly, I won’t be living in a trailer, but it won’t be 85th and Madison. I’m pulling out of the market right away.
Thanks so much for the help. Now, let’s go have a corned beef at Katz’s!”
Risky Investing Is an Option, Not a Starting Point
Conventional planning starts and stops with your investing at risk. It sets a high spending target that you can only reach with high probability if you invest in high yield securities. But that high probability is not 100 percent. It can be as low as 80 percent. In this case, you have a 20 percent, a 1 in 5, probability of losing all your financial assets in retirement, including on day 1.
Many retired households are still playing the market even though they are spending far less than they could were they to invest in a ladder of TIPS. They likely don’t realize they are doing so. This is where MaxiFi can help. It’s safety-first lifetime budgeting and consumption smoothing lets you see if you are spending less than you could were you to invest safely. If you are and you are happy with your spending, ask yourself why you are investing at risk? Perhaps you are doing so to produce a higher bequest for your children? If so, ask them if they want their inheritance to be up for grabs or whether they’d prefer inheriting a sure thing. At the margin, what appears to be your money is actually their money. If you aren’t investing at risk for your kids, are you investing at risk simply for the prospect of damaging your financial future?
And now ads from your sponsor — ME!
Larry,
I'm retired and use Maxfi for financial guidance. Thank you. That being said it's difficult for me to feel sorry for Hypothetical Sandy who has $3m in real estate, $5 m in regular assets, and $5 in retirement. If she lost 50% of her regular assets and retirement in a crash, I think she would see the light and still be ok. I'm sure there are many retired people out there that have Hypothetical Sandy's kind of wealth. I'm also sure that there are many more that have considerably less. Have you written any articles on a hypothetical baby boomer starting retirement with say $1m (which I understand is more than most) or is MaxFi only useful for the multi-millionaires ?
Building a cash-flow machine is how I personally stretch my money out over a lifetime.
If you rely entirely on a volatile stock portfolio, a bad market downturn forces you to sell off assets at a discount just to pay your bills.
That’s exactly how you get hurt.
By splitting the workload—using PAYG to handle my current lifestyle expenses and keeping VT tucked away for the long run—I never have to touch my core assets during a crash.
I think of my portfolio as two separate buckets.
The growth bucket buys you time, while the yield bucket buys you lifestyle.
When you automate both, you stretch your capital further without ever having to worry about market timing or decision fatigue.